

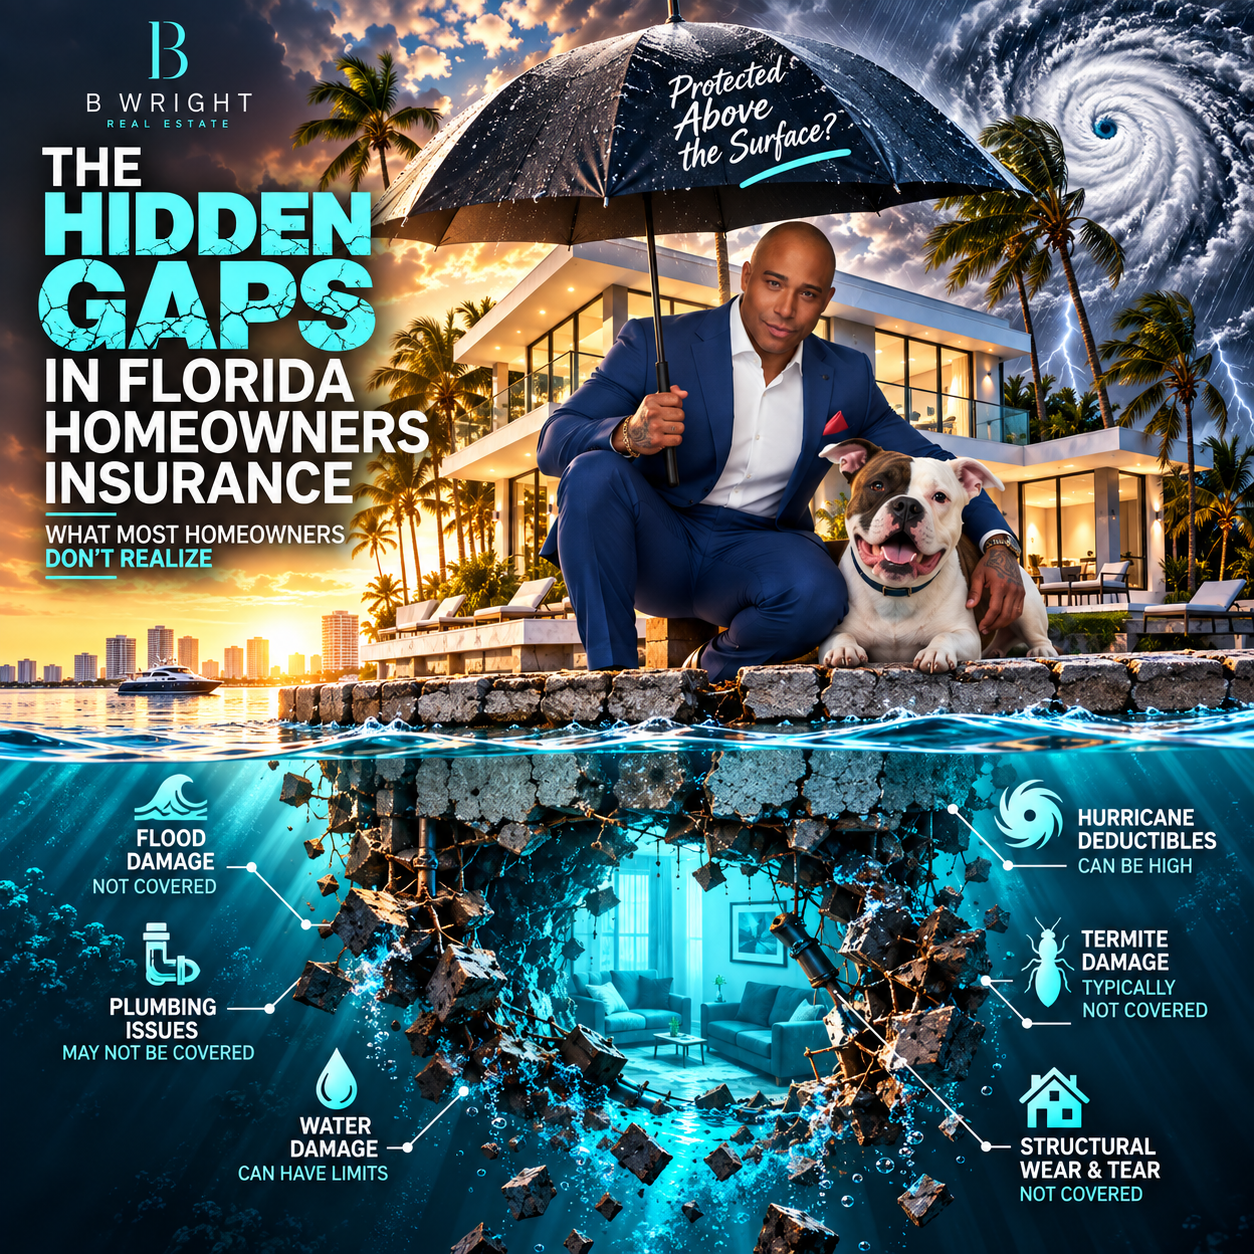
Paying for homeowners insurance every month does not guarantee that a claim will fully protect your savings. That frustration is real, and it's one that more homeowners are feeling as premiums keep climbing. According to the Insurance Information Institute, average homeowners insurance premiums have risen sharply in recent years, yet higher costs do not automatically translate into stronger protection.
The disconnect happens because most people judge their coverage by what they pay, not by what the policy actually says. A policy can look complete on the surface while still leaving significant room for out-of-pocket costs after a loss. The fine print is where that exposure lives, and most homeowners never read it until they have to file a claim.
This article is not just a rundown of policy jargon. It's a practical guide to the five gaps that create the biggest mismatch between what homeowners expect and what insurers may actually pay. Knowing where these gaps exist puts you in a position to fix them before they cost you.
Why Your Dwelling Limit May Be Too Low When Rebuilding Costs Jump
The single biggest financial exposure in most homeowners policies is an outdated dwelling limit. Coverage A, which pays to rebuild your home after a covered loss, is only useful if the limit reflects what it actually costs to rebuild today, not what you paid for the house or what it would sell for on the market.
Market value and replacement cost are two completely different numbers. Market value includes the land and reflects buyer demand in your area. Replacement cost is what a contractor would charge to rebuild the same structure from scratch using current labor rates and materials. In many markets, those numbers are far apart, and using the wrong one as your benchmark can leave you severely underinsured.
Reconstruction costs have continued to rise due to inflation, persistent labor shortages, and higher material prices. A dwelling limit that was accurate three years ago may now fall short by tens of thousands of dollars. If you have also made improvements to your home since the policy was written, such as a kitchen renovation, a finished basement, or a bathroom addition, those upgrades add real value to the rebuild cost but do not automatically update your coverage.
Check your declarations page for three things right away. First, find your dwelling limit and compare it to a current replacement cost estimate, which your insurer or an independent appraiser can provide. Second, look for an inflation guard endorsement, which automatically adjusts your limit over time to keep pace with rising costs. Third, note when your policy was last updated and whether any home improvements happened after that date.
Setting a dwelling limit based on your purchase price is one of the most common and costly mistakes homeowners make. The goal is to cover what it costs to rebuild, and that number needs to reflect the current construction environment, not the one that existed when you first bought the house.
Why Your Deductible May Be Much Bigger Than You Remember
A covered claim is not the same as a free claim. Before your insurer pays anything, you are responsible for the deductible, and many homeowners are surprised to find out how large that number actually is when a storm rolls through.
Most people assume their policy has a single deductible, but many policies carry more than one. Standard deductibles apply to most covered losses, but separate deductibles often apply specifically to wind, hail, hurricanes, or named storms. These are not the same number, and the difference matters enormously depending on where you live.
The structure of these deductibles is where things get expensive. Many wind and hurricane deductibles are written as a percentage of your dwelling coverage rather than a flat dollar amount. A 2% deductible on a $400,000 home means you owe $8,000 out of pocket before insurance contributes a single dollar to repairs. At 5%, that number jumps to $20,000. Most homeowners who set up their policies years ago never converted those percentages into actual dollar amounts, which means the real cost only becomes clear after a claim.
This type of deductible structure is especially common in hurricane-prone states like Florida, Texas, and the Carolinas, but hail deductibles have also become more widespread across the Midwest and Great Plains. The risk is not limited to coastal areas, and assuming a standard deductible applies to every type of loss is a mistake that can be financially painful.
Go through your declarations page and convert every percentage-based deductible into a dollar figure right now. If you have a $350,000 dwelling limit and a 3% named storm deductible, you are looking at $10,500 out of pocket in the event of a hurricane claim. Knowing that number in advance gives you the chance to build that reserve into your finances or explore whether a policy with a flat deductible makes more sense for your situation.
Being capable of managing a claim confidently starts with knowing exactly what you owe before insurance steps in. That clarity is entirely within reach once you do the math.
Why a Covered Claim Can Still Produce a Disappointing Payout
Whether a loss is covered is only half the question. How that loss is valued determines the size of the check you actually receive, and this is where many homeowners feel blindsided.
Two policies can both cover the same roof damage while paying out very different amounts. The difference comes down to whether your policy uses replacement cost value or actual cash value to settle claims. Replacement cost pays what it costs to repair or replace the damaged item at current prices. Actual cash value deducts depreciation first, so you receive what the item was worth at the time of the loss, not what it costs to fix it today.
Depreciation hits hardest on items that age quickly or carry high replacement costs. Roofs are the most significant pressure point. A 15-year-old roof that costs $18,000 to replace might be valued at a fraction of that under actual cash value rules, leaving you to cover the gap out of pocket. Some insurers have also introduced roof schedules or cosmetic damage exclusions that apply stricter settlement terms to older roofs, regardless of how the policy reads elsewhere.
Personal belongings follow the same logic. Electronics, appliances, and furniture all depreciate over time, so an actual cash value settlement for a house fire can fall well short of what it costs to replace everything at today's retail prices.
When reviewing your policy, look for specific language rather than assuming. Terms like "actual cash value," "roof settlement schedule," or "cosmetic damage exclusion" signal that your payout may be reduced even when the underlying claim is valid. A replacement cost endorsement for personal property or an upgraded roof settlement option can close that gap, but only if you add it before the loss occurs.
Why Your Valuables May Be Covered Only Up to a Small Cap
Standard personal property coverage can look generous until you check what it actually pays for specific categories of items. Most HO-3 policies include sublimits for jewelry, watches, furs, firearms, collectibles, camera equipment, and musical instruments. These caps exist regardless of how high your total personal property limit is.
A ring worth $7,500 may only be covered up to $1,500 under a standard policy's jewelry sublimit. A professional camera kit worth $4,000 might hit a similar ceiling. The total personal property limit on your declarations page will not protect these items beyond the category cap, even if plenty of coverage appears to remain.
Scheduled personal property coverage, sometimes called a floater, solves this problem by covering specific high-value items individually at their appraised or agreed value. Each item gets its own limit, often with broader coverage than the base policy provides, including protection against accidental loss in some cases.
A home inventory is the most practical tool for identifying where your exposure is. Go room by room, list items that would be expensive to replace, and compare those values against your policy's sublimits. Pay particular attention to items you have acquired since the policy was written, since new purchases rarely trigger automatic coverage updates. The items that would be hardest to replace from savings are the ones most worth scheduling.
Why Some of the Costliest Losses Are Excluded Altogether
Some losses are not underpaid. They are simply not covered at all, and flood damage is the clearest example. A standard homeowners policy does not cover flooding from rising water, storm surge, or overland runoff. That exclusion applies regardless of how severe the storm is or how close you are to a body of water.
The confusion usually comes from how water damage is described. A burst pipe that suddenly soaks your floors is typically a covered loss. Rainwater that backs up through a storm drain and fills your basement is not. The distinction between sudden internal water damage and external flooding is significant, and many homeowners only discover it after submitting a claim.
Flood risk is also not limited to coastal zones or FEMA high-risk flood areas. Heavy rainfall events, overwhelmed drainage systems, and rapid snowmelt can all cause flooding in areas that many homeowners consider low-risk. Separate flood insurance is available through the National Flood Insurance Program as well as private carriers, and it requires its own application and waiting period, so it cannot be added reactively once a storm is already approaching.
Two other exclusions worth asking about are sewer backup coverage and ordinance or law coverage. Sewer backup is often available as an endorsement and covers damage from water or sewage that reverses through drains into your home. Ordinance and law coverage pays the added cost of rebuilding to current building codes after a covered loss, which can be significant in older homes where code compliance requires upgrades beyond simple restoration.
How to Do a 15-Minute Insurance Gap Check This Week
Turning awareness into action does not require a long afternoon or a background in insurance. A focused review of your declarations page and policy documents can surface the most important gaps in under 15 minutes if you know what to look for.
Work through these steps in order:
- Pull your declarations page and locate your dwelling limit, personal property limit, liability limit, and every deductible listed. Write them down in one place so you can see the full picture at once.
- Convert all percentage deductibles into dollar amounts using your current dwelling limit. A 2% wind deductible on a $350,000 home is $7,000 out of pocket. Do that math for every percentage-based deductible on the page.
- Scan for valuation language throughout the policy. Look for terms like "actual cash value," "replacement cost," "roof settlement schedule," or "cosmetic damage exclusion" so you understand how claims will be paid, not just whether they are covered.
- Compare your high-value items against category sublimits. Check jewelry, electronics, instruments, and collectibles against the caps in your policy. Note anything that exceeds the sublimit and may need to be separately scheduled.
- Review your exclusions section for flood, sewer backup, wear and tear, and gradual damage. If flood coverage is absent and you have any water exposure risk, contact your agent about separate flood insurance options.
- Write down your questions before your next agent conversation. Bring specific numbers and policy terms to that call rather than general concerns. Asking whether your dwelling limit reflects current rebuild costs in your area, or whether a replacement cost endorsement is available for your roof, will get you more useful answers than asking if you have "good coverage."
Scheduling this review before your renewal date gives you the most leverage, since that is when coverage changes and endorsements can be added without a mid-term adjustment.
Final Thoughts
Most homeowners assume that having a policy means having protection. But the gap between what you think is covered and what actually gets paid out can be wide enough to cause serious financial damage.
The five gaps covered here are not edge cases. Outdated dwelling limits, percentage-based or separate deductibles, actual cash value payouts, category caps on valuables, and exclusions for flood or maintenance-related damage show up regularly in real claims. They catch people off guard precisely because nothing about them is obvious from the outside of a policy.
Knowing how replacement cost coverage differs from actual cash value, why a 2% hurricane deductible on a $400,000 home means $8,000 out of pocket before insurance pays a cent, and how a standard HO-3 policy leaves flood damage entirely unaddressed gives you a real advantage. That kind of specific knowledge is what separates a homeowner who gets made whole after a loss from one who doesn't.
You are fully capable of closing these gaps. Running a policy audit does not require an insurance degree. It requires pulling out your declarations page, checking your coverage limits against current rebuild costs, reviewing how your deductibles are structured, and asking your agent direct questions about exclusions and endorsements.
The real question is not only whether you are covered, but how much you may still owe after a claim. A short policy review now costs nothing. Finding a gap during a claim costs far more.
Check out this article next